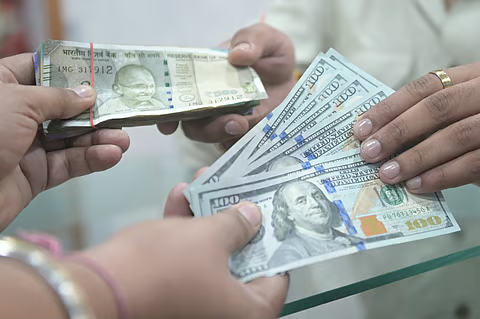
Higher returns on foreign-currency deposits are drawing overseas Indians, as the central bank seeks to strengthen forex reserves and support the rupee
Indian banks are attracting renewed interest from non-resident Indians (NRIs) with higher returns on Foreign Currency Non-Resident (Bank), or FCNR(B), deposits, as the Reserve Bank of India (RBI) steps up efforts to bring more foreign currency into the country.
The latest initiative echoes the RBI’s response to the 2013 “Taper Tantrum”, when a special FCNR(B) mobilisation programme attracted more than $30 billion in inflows. The current scheme comes amid pressure on the rupee, higher oil prices and changing global financial conditions.
FCNR(B) deposits allow eligible NRIs to keep their savings in approved foreign currencies such as US dollars rather than converting them into rupees. Both the principal and interest remain denominated in the chosen foreign currency, protecting depositors from direct exposure to a fall in the rupee.
The offer has become particularly attractive for Indians in the UAE and other Gulf countries. Several Indian banks have raised dollar deposit rates, with some offers reaching around 6-7.1 per cent, while other lenders have subsequently advertised rates of up to 7.4 per cent for selected tenures.
-
The higher rates have been supported by an RBI fixed-rate swap facility introduced in June at 1.5 per cent for eligible FCNR(B) deposits
-
The mechanism reduces banks’ currency-hedging costs, giving them greater room to offer competitive returns
The RBI has also allowed banks to issue guarantees, standby letters of credit and other credit facilities against eligible FCNR(B) deposits. While this creates additional financing possibilities, it can also introduce leverage and higher risks for investors.
For NRIs, the distinction is important. A conventional FCNR(B) deposit can provide dollar-denominated returns without direct rupee depreciation risk, but funds are generally locked in for three to five years. Early withdrawal can affect returns and may involve penalties or other costs.
The broader objective is clear: attract overseas Indian savings, rebuild foreign-exchange reserves and strengthen confidence in the rupee. Recent data has shown the potential scale of the strategy, with India’s forex reserves reaching a record $785.7 billion in early September after a sharp increase in foreign-currency inflows.